
Quick Summary
Oil is back at the centre of this week's market discussion. The U.S. Energy Information Administration reports that average global oil prices rose to $91 a barrel in August, $7 above July, with constrained Middle Eastern exports and falling inventories supporting prices. Its September outlook was completed on September 3, so it is a dated baseline for the week ahead. EIA September outlook
Equities enter September 14–18 with that energy pressure meeting a major policy test. The S&P 500 lost 0.8% in the week ended September 11, while the Russell 2000 fell 2.4%, according to Nasdaq Dorsey Wright. Our interpretation is a selective market: oil can support producers while weighing on demand, margins and valuations elsewhere. Canada's CPI release and Wednesday's Federal Reserve decision are the central checkpoints. Nasdaq weekly review
Market Tone
The tone is cautious, selective and sensitive to oil and interest rates.
Two scenarios deserve attention. If crude settles and bond yields ease, equity participation could improve beyond a few resilient groups. If energy costs remain elevated and policy communication reinforces inflation concerns, the pressure could spread to consumer demand and corporate margins. These are conditional interpretations, not forecasts of the Fed's decision.
The U.S. midterms add a political backdrop. The federal general election is scheduled for November 3, 2026. Campaign statements on trade, energy and fiscal policy may affect sentiment, but proposals should be distinguished from enacted policy. A midterm-year label alone offers little evidence about this week's direction. Federal Election Commission
SPY / QQQ Context
SPY: SPY tracks the S&P 500, making participation across large U.S. companies a useful companion to its price action. Nasdaq Dorsey Wright's September 11 review reports deteriorating participation within the index. The educational test is whether rebounds become broader and survive the next session. Continued small-cap weakness alongside resilient large companies would keep the recovery selective. The S&P 500's weekly return above is an index return, not a quoted SPY fund return. State Street SPY overview, Nasdaq weekly review
QQQ: QQQ follows the Nasdaq-100, a benchmark of large non-financial Nasdaq-listed companies spanning several sectors. For this week's research, monitor whether semiconductor, software and other major growth businesses participate together. A steadier bond market could help valuations; renewed yield pressure could offset healthy company fundamentals. QQQ's response relative to SPY after the Fed announcement will be more informative than the first few minutes of trading. Invesco QQQ overview
Technology's relative resilience is useful context, but it does not establish a fresh breakout or broad market leadership. Sustained participation and follow-through remain the tests.
TSX / Canadian Market Context
The Canadian framework is mixed: energy exposure can offer support, while tariff uncertainty and persistent fuel costs complicate the domestic outlook. Financials, energy and materials are central groups to monitor within Canada's broad equity market. Their responses to rates, credit conditions and different commodities can diverge. S&P/TSX Composite index overview
The Bank of Canada held its policy rate at 2.25% on September 2. Its accompanying remarks described a recovery facing renewed trade uncertainty and increasing upside inflation risks from oil. The Bank also warned that uncertainty could delay investment and hiring. This supports a cautious Canadian research stance without assuming every exporter or domestic business faces the same outcome. Bank of Canada decision, opening statement
Monday's inflation and manufacturing reports offer different lenses on that tension. Wednesday's deliberations explain the earlier policy decision; they are not a new rate announcement. For TSX confirmation, watch whether energy resilience is joined by banks and other domestic groups, and whether the Canadian dollar amplifies or offsets costs for individual businesses.
Sector Map
The map below combines observed relative-strength evidence with conditional economic effects; it is not a weekly sector-return ranking.
Stronger or Improving
Technology, relative to industrials: Nasdaq Dorsey Wright places technology ahead of industrials in its September 11 sector rankings. The relevant question is whether that resilience extends across multiple technology industries as rates settle. Nasdaq weekly review
Oil producers, conditional tailwind: Higher realised crude prices can support producer revenue, making U.S. and Canadian energy companies a useful research theme. Company costs, hedges, production and balance sheets still matter. EIA's forecast also anticipates eventual supply recovery, so current tightness should not be projected indefinitely. EIA September outlook
Weaker or More Selective
Industrials: Nasdaq's review identifies a slowdown in industrials' relative strength. That makes new orders, output and price pressures useful confirmation points in this week's data. Nasdaq weekly review
Fuel-intensive and consumer-sensitive businesses: As a scenario, sustained fuel inflation can pressure transport margins and leave households with less room for discretionary spending. Pricing power and hedging can change the impact substantially; higher oil does not make every company in these groups weaker.
Rate-sensitive property and speculative growth: These remain selective if yields rise. Lower yields could support a rebound, while tighter financing conditions could extend pressure. Their potential response is a watchlist framework, not an assertion of measured weekly sector losses.
Watchlist Themes
Energy strength versus demand damage: Compare producer resilience with the response of transport and consumer businesses. Oil rising alongside weakening demand indicators would carry a different message from oil rising alongside stronger economic activity.
Technology breadth after the Fed: Look for participation across semiconductors, software and other growth businesses. A move concentrated in very few companies offers less evidence of a durable improvement.
Canadian trade exposure: Examine where companies earn revenue, source inputs and incur costs. The same tariff headline can have different implications for a domestic service business, a manufacturer and a commodity exporter.
Financials and credit: Follow banks as a test of whether the broader economy can absorb higher costs. Credit quality and demand for borrowing matter alongside changes in interest rates. Friday's scheduled stress-testing discussion adds supervisory context.
Risk Notes
- Oil-supply and geopolitical headlines can produce overnight gaps and rapid reversals.
- Wednesday combines several releases with the Fed decision; the first market reaction may change during the press conference.
- Higher policy rates, lower rates or an unchanged decision can each produce different outcomes depending on expectations and guidance.
- Strong sectors can become crowded, while weaker groups can rebound sharply.
- Currency movements, tariffs and company-specific exposures can make U.S. and Canadian returns diverge.
- Position sizing, liquidity, diversification and a clearly defined point at which a research thesis no longer holds are core risk considerations. Stop orders may execute away from the intended price during gaps.
What to Watch This Week
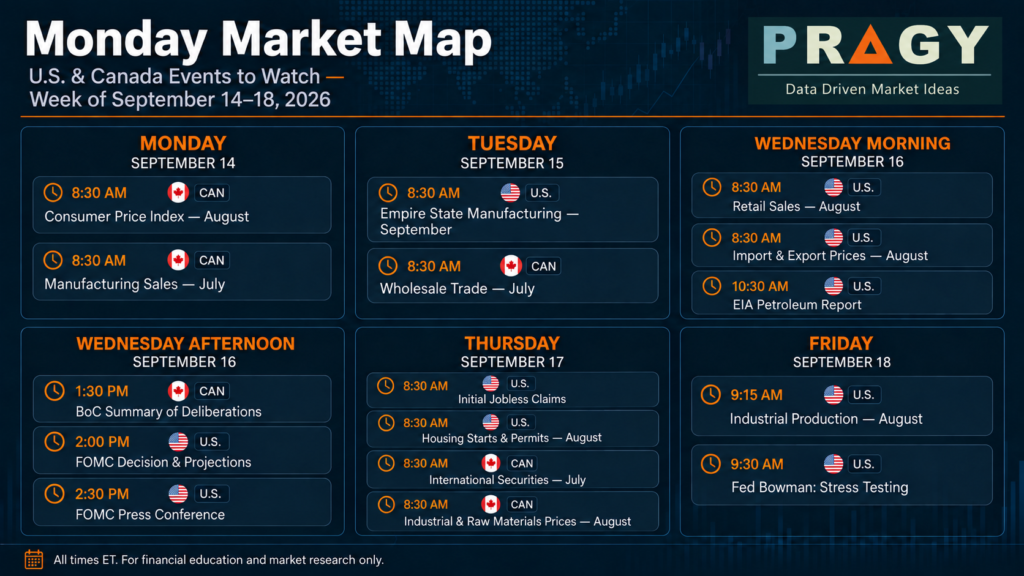
Monday and Tuesday: Canada's CPI, manufacturing sales and wholesale trade help separate price pressure from activity. The Empire State survey provides an early September view of U.S. manufacturing conditions.
Wednesday: Retail sales and import/export prices set the morning context. EIA inventories then test the oil narrative. At 1:30 PM ET, the Bank of Canada publishes deliberations from its September 2 decision. The FOMC decision and projections follow at 2:00 PM, with the press conference at 2:30 PM. Watch equities, yields and the dollar together. Bank of Canada event notice, Federal Reserve calendar, FOMC meeting schedule
Thursday and Friday: Claims, housing construction, Canadian upstream prices and U.S. industrial production test whether the policy reaction has support from activity data. Compare SPY and QQQ follow-through with Canadian financials and energy. Broad participation after the announcements would be more constructive than isolated price spikes.
Weekly Calendar
Selected events for September 14–18, 2026. All times are Eastern Time (ET; EDT, UTC−4 during this week). Importance is shown as “Not specified” because the issuing organizations do not provide comparable impact ratings. Dates and times are sourced in the notes below.
| Date | Time | Country | Event | Importance | Why It Matters |
|---|---|---|---|---|---|
| Mon, Sep. 14 | 8:30 AM | Canada | Consumer Price Index, August | Not specified | Tests whether energy inflation is spreading. |
| Mon, Sep. 14 | 8:30 AM | Canada | Manufacturing sales, July | Not specified | Tracks factory activity amid trade uncertainty. |
| Tue, Sep. 15 | 8:30 AM | U.S. | Empire State Manufacturing Survey, September | Not specified | Early regional read on orders and costs. |
| Tue, Sep. 15 | 8:30 AM | Canada | Wholesale trade, July | Not specified | Adds evidence on Canadian business demand. |
| Wed, Sep. 16 | 8:30 AM | U.S. | Retail sales, August | Not specified | Measures nominal consumer spending. |
| Wed, Sep. 16 | 8:30 AM | U.S. | Import and export price indexes, August | Not specified | Adds cross-border price context. |
| Wed, Sep. 16 | 10:30 AM | U.S. | EIA Weekly Petroleum Status Report, initial tables | Not specified | Updates crude and fuel inventory balances. |
| Wed, Sep. 16 | 1:30 PM | Canada | Bank of Canada Summary of Deliberations | Not specified | Explains the September 2 policy discussion. |
| Wed, Sep. 16 | 2:00 PM | U.S. | FOMC decision and economic projections | Not specified | Reframes rates, inflation and growth expectations. |
| Wed, Sep. 16 | 2:30 PM | U.S. | FOMC press conference | Not specified | Clarifies the decision and policy outlook. |
| Thu, Sep. 17 | 8:30 AM | U.S. | Initial jobless claims | Not specified | Offers a timely labour-market check. |
| Thu, Sep. 17 | 8:30 AM | U.S. | Housing starts and building permits, August | Not specified | Tests interest-sensitive construction demand. |
| Thu, Sep. 17 | 8:30 AM | Canada | International transactions in securities, July | Not specified | Tracks cross-border investment flows. |
| Thu, Sep. 17 | 8:30 AM | Canada | Industrial product and raw materials price indexes, August | Not specified | Tests upstream price pressure. |
| Fri, Sep. 18 | 9:15 AM | U.S. | Industrial production and capacity utilization, August | Not specified | Checks output across factories, mining and utilities. |
| Fri, Sep. 18 | 9:30 AM | U.S. | Fed Vice Chair for Supervision Bowman: Stress Testing | Not specified | Provides banking-supervision context. |
The EIA entry refers to its initial tables and highlights; the full report is released later. The FOMC meets September 15–16, with the decision on Wednesday. Event schedules can change.
Source Notes
Prepared September 14, 2026 for the week of September 14–18. Market observations use information available through September 11; the EIA forecast's earlier cutoff is identified above. The oil, election and trade themes began with the supplied editorial notes. Linked primary publications support factual statements; forward-looking sector and market interpretations are Pragy's conditional research framework.
Calendar sources consulted September 14, 2026:
- Statistics Canada — September 14–25 release schedule: Canadian CPI, manufacturing, wholesale trade, securities flows, and industrial/raw-material prices; standard release time 8:30 AM ET.
- Statistics Canada — CPI portal: corroborates the September 14 CPI date.
- New York Fed — September calendar: Empire State survey and initial claims.
- U.S. Census Bureau — release schedule: retail sales and housing construction.
- BLS — September release schedule: import/export prices. U.S. CPI was scheduled September 11, outside this week's calendar.
- EIA — Weekly Petroleum Status Report and release timing: September 16 date and 10:30 AM ET initial release.
- Bank of Canada — September 16 event notice: 1:30 PM ET deliberations.
- Federal Reserve — September calendar and meeting schedule: FOMC decision, projections, press conference and Bowman's stress-testing discussion.
- Federal Reserve — G.17 release schedule: September 18 industrial production at 9:15 AM ET.
Author Disclosure
Disclosure: The author may hold positions in securities, ETFs, leveraged ETFs, options, or related instruments discussed.
Disclaimer
This content is for financial education and market research only. It is not investment advice, financial planning, portfolio management, tax advice, legal advice, or a recommendation to buy, sell, or hold any security. Trading and investing involve risk, including possible loss of capital. Readers are responsible for their own decisions and should consult a qualified financial professional before making financial decisions.